

Payday Cash Advance TriceLoans

- 199.00 Reviews
- 4.7
- Downloads
- 50,000+
Our take on Payday Cash Advance TriceLoans from Appgk
When an unexpected bill lands before payday, the hardest part is often knowing where to begin. Payday Cash Advance TriceLoans is a finance app from Trice Loans that aims to make that first step simple: open the app, review the available borrowing path, and decide whether a short-term cash advance fits your situation. I found the appeal easy to understand, especially for someone who wants to handle the process from a phone rather than visit a branch.
My main advice is to treat it as a tool for a temporary cash gap, not as a general solution for ongoing money problems. The app’s store summary focuses on fast access and no credit check, but speed should never replace careful reading. Before accepting anything, I would check the repayment amount, timing, and every charge shown in the application flow. A quick application is useful only when the repayment plan is equally clear.
What to expect before you apply
TriceLoans sits in the short-term borrowing part of the finance category. It is free to install, has an Everyone content rating, and the developer is listed as Trice Loans. The app has reached over 50 thousand installs and holds a 4.7 average from around 7 thousand ratings, which suggests that many people have found the basic experience approachable. I still would not treat popularity as proof that a loan is suitable for every budget.
The app is aimed at people looking for a payday cash advance or instant cash advance rather than long-term financial planning. That distinction matters. If I needed help covering a one-off timing problem, such as a necessary household expense arriving before my normal income, I would consider reviewing the offer. If I were trying to pay rent, utilities, or existing debt repeatedly with new advances, I would step back and look for a more sustainable option first.
Best Parts of Payday Cash Advance TriceLoans
Things to Keep in Mind About Payday Cash Advance TriceLoans
There is also a practical difference between installing a loan app and receiving money. The application may be quick to begin, but the useful outcome depends on eligibility, the information requested, the terms presented, and the timing of any transfer. I would keep realistic expectations and avoid making a purchase or promising payment until the app clearly shows that the advance has been approved and the funds are available.
The current version is 1.1.6, and the app supports Android 7.0 or later. That makes it accessible on many older Android phones, which is helpful for users who do not own a recent device. The app is free to download, while its listing also shows in-app purchase items from $1.99 to $4.99. Because borrowing costs and app purchase items are not the same thing, I would examine each screen carefully so I understand what I am agreeing to rather than assuming every displayed amount relates to the advance itself.
News and Features Related to Payday Cash Advance TriceLoans

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Who will get the most value
I think the strongest fit is a user who already knows exactly how much money is needed, why it is needed, and when repayment should be manageable. That preparation makes the application less emotional. Instead of borrowing the maximum amount simply because it appears available, I would calculate the smallest amount that solves the immediate problem and leave a buffer in the regular budget for repayment.
For example, imagine a phone bill and a necessary repair arriving in the same week, while your normal income is due shortly afterward. I would first total the essential cost, remove anything that can wait, and then use TriceLoans only to cover the remaining shortfall if the final repayment fits comfortably after payday. I would save a screenshot or note of the agreed amount and due date, then set a reminder outside the app. That small habit prevents the common mistake of remembering the borrowed amount but forgetting the repayment schedule.
Don't want to read the full review?
The app is less suitable for someone comparing several long-term financing choices. A credit union, bank, employer advance, or carefully chosen personal loan may offer a better structure for a larger expense. A nonprofit money adviser may be more useful when the problem is recurring. TriceLoans can be convenient for a narrow, short-lived need, but convenience is not the same as affordability.
Starting carefully and reaching the first useful result
Install with a clear purpose
Before opening the application, I would write down three things: the exact amount needed, the latest acceptable repayment date, and the maximum total repayment I can handle. This takes only a minute and gives the application a firm boundary. Without those limits, it is easy to focus on the amount offered instead of the amount that makes sense.
Screenshots
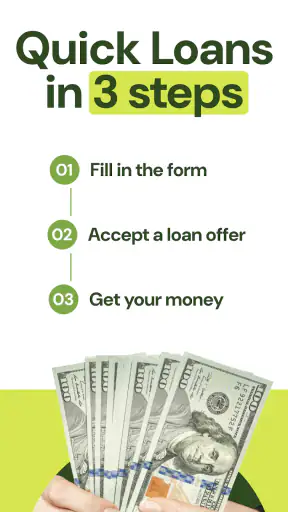
I would also make sure the phone is running Android 7.0 or newer and that the device is secure. A finance app deserves the same care as mobile banking: use a screen lock, avoid public Wi-Fi during sensitive steps, and do not share verification codes with another person. These are not special TriceLoans features; they are sensible habits whenever personal and financial information is involved.
Because the app is free to install, there is no reason to rush into borrowing just to justify the download. I could install it, review the opening screens, and leave if the terms do not suit my situation. The first meaningful success is not merely completing an application. It is reaching a clear decision with a repayment plan I understand.
Prepare before entering details
A first-time user will have a smoother experience by keeping the relevant personal and income information close at hand. I would use consistent details throughout the application and pause if a question is unclear rather than guessing. Incorrect or mismatched information can create delays, and rushing through a financial form is rarely worth it.
I would read every disclosure presented before moving forward, especially the total repayment, any applicable fee, the payment date, and what happens if repayment is late. The store summary highlights no credit check, but that should not be interpreted as no assessment at all. A provider may still need information to decide eligibility and repayment ability. The important question for me would be whether the final offer is understandable and affordable, not whether one particular check is skipped.
Another useful preparation step is to decide how I will repay before applying. If the plan depends on an uncertain payment, a future sale, or another loan, I would not regard it as a safe plan. A short-term advance works best when the repayment source is already expected and the timing is reasonably dependable.
The first successful action
Once inside the app, I would move slowly through the application and stop at the first screen that presents actual terms. That is the point where browsing becomes a financial decision. I would compare the amount received with the total amount due, check the stated timing, and confirm that the payment will not interfere with essentials such as food, housing, transport, or existing commitments.
If the offer works, I would accept only after saving the key details in a private note. I would record the amount borrowed, the total repayment, the due date, and the name of the provider. I would then set a calendar reminder for several days before the due date, followed by a second reminder on the due date itself. This is one of the most useful workflows for a short-term finance app because it moves repayment planning outside the excitement of approval.
If the offer does not work, declining is also a successful outcome. I would close the process rather than borrowing simply because I had already entered information. The app should serve the budget, not pressure the budget into serving the app.
What can feel confusing
The phrase “instant cash advance” can create the impression that money will always arrive immediately. I would separate three stages in my mind: submitting information, receiving a decision, and seeing usable funds. Those stages may not feel identical, and the practical timing can depend on the application and the financial service involved. I would not schedule an urgent payment until the funds are visibly available.
Another possible source of confusion is the difference between the app’s free installation and the financial cost of borrowing. Free download does not mean free credit. Likewise, the in-app purchase range shown in the listing should not be casually treated as the cost of an advance. I would rely on the specific terms shown during the borrowing process and avoid approving anything I cannot explain in plain language.
Users may also wonder what “no credit check” means in practice. I would read it as a description of the application’s positioning, not as a promise that approval is automatic. Eligibility can still depend on the information submitted and the provider’s assessment. If the app does not present a clear reason for a decision or if a screen seems inconsistent, I would stop and use the available support route rather than repeatedly submitting applications.
Privacy is another area where I would be deliberate. A finance application may require sensitive information to process a request, so I would review each permission or information request in context and avoid uploading documents through unofficial channels. I would also verify that messages and notifications genuinely relate to the application before responding. Scammers often imitate financial services, and a legitimate-looking name alone is not enough reason to share a code or payment.
How it compares with familiar alternatives
Compared with visiting a bank branch, TriceLoans is more convenient for someone who wants to start from an Android phone and handle the process privately. Compared with a traditional personal loan, a payday-style advance is generally more focused on a short gap than on spreading a larger expense over a longer period. That focus can be helpful when the need is small and temporary, but it can become expensive or stressful when repayment is uncertain.
A credit card may offer more flexibility for a planned purchase, while an overdraft may be simpler for a brief account shortfall. Neither option is automatically better; the right comparison is the total cost, repayment timing, and consequences of missing a payment. For a recurring cash-flow problem, a budget review or advice service is usually more valuable than moving from one advance to another.
The practical advantage I see here is the direct, mobile-first path. The practical disadvantage is that the same simplicity can make borrowing feel less serious than it is. I would use the app as a decision aid for a specific emergency, not as a replacement for an emergency fund, a bank relationship, or professional financial advice.
My next-step routine after approval
After receiving an advance, I would immediately separate the repayment amount from everyday spending if possible. Even moving it into a different account or marking it clearly in a budgeting app can reduce the temptation to treat the full balance as available money. I would then check the repayment reminder and keep the app’s confirmation details somewhere secure.
If my circumstances changed, I would contact the provider through the app’s official support path as early as possible rather than waiting until the due date. I would not assume that an extension, rollover, or altered payment arrangement is automatic. Any new terms should be read from the beginning, including the new total cost and final date.
For someone considering repeated use, I would make a simple review after the first repayment: did the advance solve a one-time timing issue, or did it leave the next pay period short? If the second answer is true, the next step should be reducing the underlying pressure, not immediately applying again. That is where a bank adviser, credit union, employer support program, or nonprofit counselor may be a better choice.
My final view for first-time users
I found Payday Cash Advance TriceLoans easiest to understand when I approached it with a narrow goal and a written repayment plan. Its free installation, broad Android compatibility, and mobile format make it approachable, while the strong average rating and growing install base indicate that the basic product has attracted substantial interest. Those points make it worth examining, but they do not remove the need to inspect the actual offer.
I would recommend trying it only when the need is genuinely short term, the repayment source is dependable, and the total cost is clear before acceptance. I would skip it when borrowing is needed for regular living expenses, when repayment depends on another loan, or when a lower-cost alternative is available. The best first step is not accepting money; it is confirming that the full repayment fits your real budget.
For a first-time user, my path would be simple: install the app, review the opening process without rushing, prepare accurate information, compare the final repayment with the amount received, and set reminders before accepting. If those checks leave me comfortable, the app may be a practical way to handle a brief cash-flow gap. If they do not, walking away is the wiser financial result.
Overall, I see Payday Cash Advance TriceLoans as a focused option for short-term borrowing rather than an all-purpose finance companion. It can make an urgent application feel more manageable, but the responsibility remains with the borrower to understand the terms, protect personal information, and plan repayment before the cash is spent.
Payday Cash Advance TriceLoans FAQ
What is Payday Cash Advance TriceLoans?
Payday Cash Advance TriceLoans appears to be a short-term lending service designed to help eligible users request a small cash advance before their next payday. The application may collect personal, employment, banking, and income information to evaluate an application. Before proceeding, review the provider’s identity, availability in your state or country, loan agreement, repayment schedule, and all applicable fees.
How does the TriceLoans application process work?
Applicants generally begin by completing an online form with contact details, income information, employment data, and banking details. The request may then be reviewed by TriceLoans or matched with a third-party lender, so approval is not guaranteed. Carefully read every disclosure before accepting an offer, because the final lender, annual percentage rate, finance charge, repayment date, and loan terms can vary.
How much does a TriceLoans payday advance cost?
The total cost depends on the lender and the terms offered after an application is reviewed. A payday advance can include interest, origination charges, processing fees, late fees, or other costs, and its annualized percentage rate may be considerably higher than that of conventional credit. Do not rely only on the advertised amount; compare the total repayment figure and confirm whether optional services are included.
When will the money arrive, and how is repayment handled?
Funding and repayment timing depend on the lender, your bank, approval time, and whether the application is completed during business hours. Approved funds may arrive quickly, but same-day delivery is not guaranteed. Repayment is commonly scheduled for a future payday and may be collected electronically from a bank account. Make sure sufficient funds are available and understand the consequences of failed or late payments.
Is Payday Cash Advance TriceLoans safe and available to everyone?
Use caution before submitting sensitive information. Confirm that the app or website clearly identifies the operating company, provides customer support and privacy terms, and explains how your data is shared with lenders or marketing partners. Eligibility, loan availability, and maximum amounts may differ by location and applicant. Never pay an upfront fee to receive a promised loan, and avoid offers requesting unusual payment methods or account credentials.











